
INVESTORS · PORTFOLIO BUILDERS
Structure decides how far the portfolio goes
Investment lending set up for the next 3 moves, not just this one
Talk to a broker$2bn
Settled
5,500+
Clients
50+
Lenders
5.0
350+ reviews
Meet your specialists
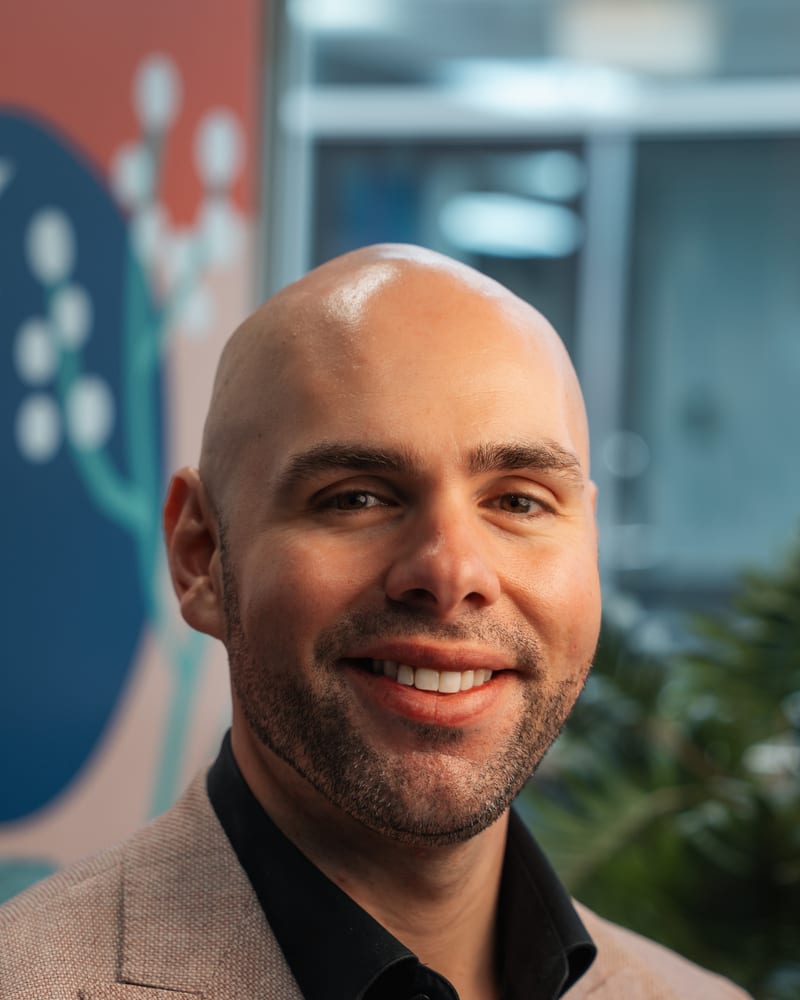
Sergio Stefano
CEO & Head Broker
Sergio founded Brokerage & Co believing people deserved more than transactional finance. As FBAA State President for SA and NT, he also works to raise industry standards.
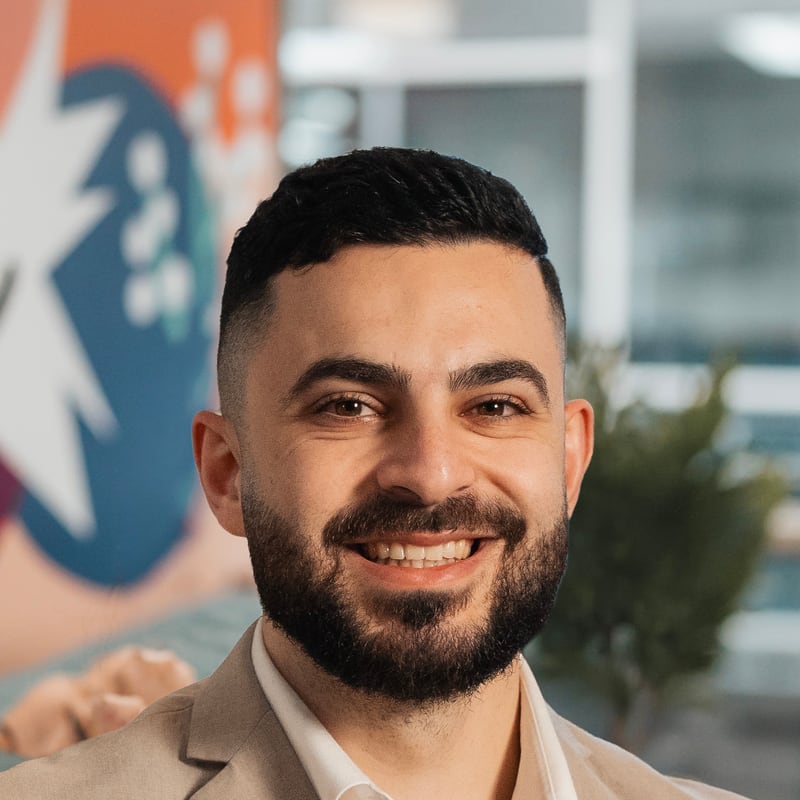
Fedi El-Daher
First Home Buyer Specialist
Fedi spent 6 years in banking while studying corporate finance at the University of Adelaide. Fedi gets to help people through some of life's biggest moments, working with first home buyers and first-time investors to make their property goals a reality.
One good investment property is a start. A well-structured portfolio is the goal. For most brokers, the job ends when this loan settles. We're already thinking about your next move: how much you can borrow, how the loan is set up, and how today's choice keeps your options open down the track.
First property or fifth, our specialist investment broker team help you buy with the long game in mind.
How much can I borrow for an investment property?
Lenders assess rental income, your existing commitments and the security mix differently, so the answer moves lender to lender. We map your realistic range early, before you fall for a property.
Should I use the equity in my home to invest?
Accessing equity is a common way to fund a deposit, and done deliberately, with clean separation and honest stress-testing, it is how most portfolios start. General information only; your accountant covers the tax side.
Interest-only or principal and interest?
Interest-only can suit some strategies and cash-flow plans, with real trade-offs later. The right answer depends on your goals, which is a conversation rather than a checkbox.
Our clients’ stories
What happens when you reach out
- 1
The conversation: 15 minutes on the plan, not just the property, so the structure serves the next 3 moves.
- 2
The structure: borrowing range, security setup, repayment type and how each choice keeps your options open.
- 3
The application: packaged properly across 50+ lenders and managed through to approval.
- 4
The next move: we review the portfolio as rates and life change, so the upgrade or the next purchase starts from a known position.
“Service like no other! I've never had a mortgage broker so on the ball. Great advice, friendly and professional.”
“Told him about a complicated financing scenario. He told us step by step the best way to proceed. I'd recommend him to anyone!”
“Outstanding service. No question was too much and no call was ever a bother. His response time reflected his work ethic.”
“Always extremely responsive and willing to go that extra yard. I could not recommend his service enough.”
Get in touch
Tell us where you’re headed
Start the conversation
Run your own numbers
Worth knowing
How is an investment loan different from a home loan?
Pricing, assessment and structure all differ: lenders treat rental income, expenses and risk differently, and the right repayment type and security setup depend on your strategy. The structural decisions matter more over 20 years than any single rate ever will.
What is cross-collateralisation, and should I avoid it?
It is when 1 loan is secured by more than 1 property. It can be convenient for the lender and constraining for you: it can limit flexibility when you sell, refinance or grow. Sometimes it is fine; often standalone securities serve investors better. We explain the trade-off for your situation.
Can I use equity in my home to invest?
Accessing equity is a common way to fund a deposit on an investment property. It has to be structured deliberately, with clear separation for your accountant and honest stress-testing of the combined position. General information only; get personal tax advice for the tax side.
Interest-only or principal and interest?
Interest-only can suit some investment strategies and cash-flow plans, and it has real trade-offs: higher long-run interest and a repayment step-up later. The honest answer depends on your goals, which is a conversation, not a checkbox.
What does your service cost an investor?
Nothing. Some brokers charge for their advice; we expressly do not. Lenders pay us on settlement, disclosed up front.
In your corner
Tell us what you're working toward and we will map the path. 1300 941 446, or book a time that suits.