
SELF-EMPLOYED · BUSINESS OWNERS
No payslips? Not a problem
Home loans for ABN income, presented by brokers who know how lenders read it
Talk to a broker$2bn
Settled
5,500+
Clients
50+
Lenders
5.0
350+ reviews
Meet your specialists
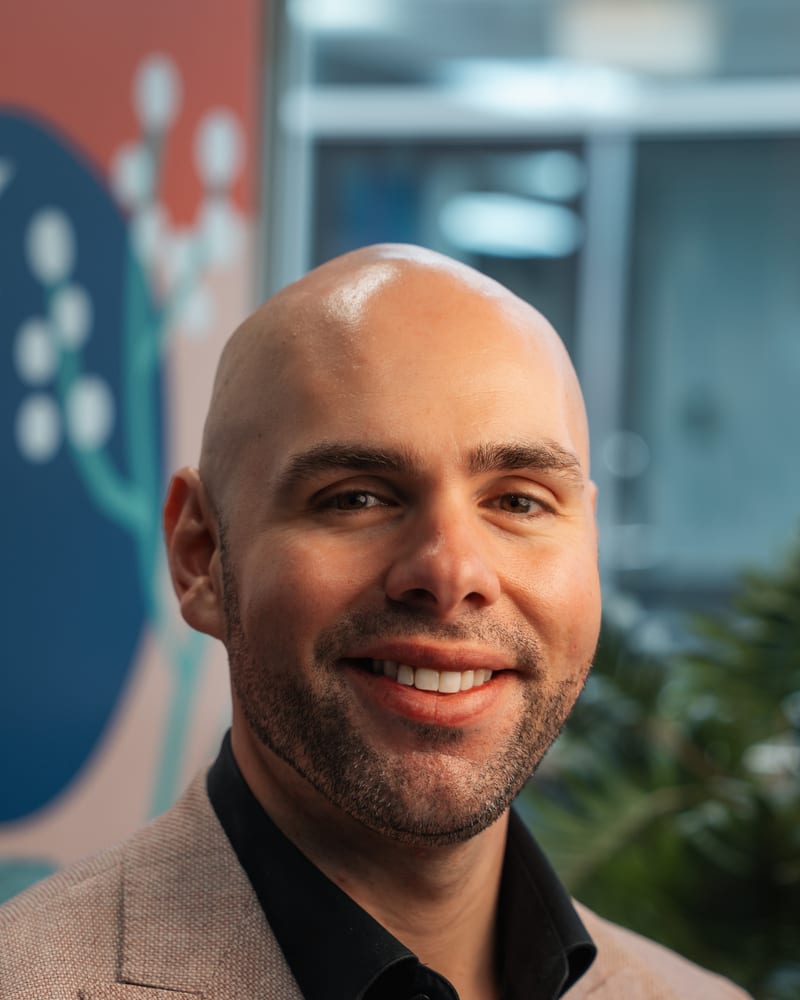
Sergio Stefano
CEO & Head Broker
Sergio founded Brokerage & Co believing people deserved more than transactional finance. As FBAA State President for SA and NT, he also works to raise industry standards.
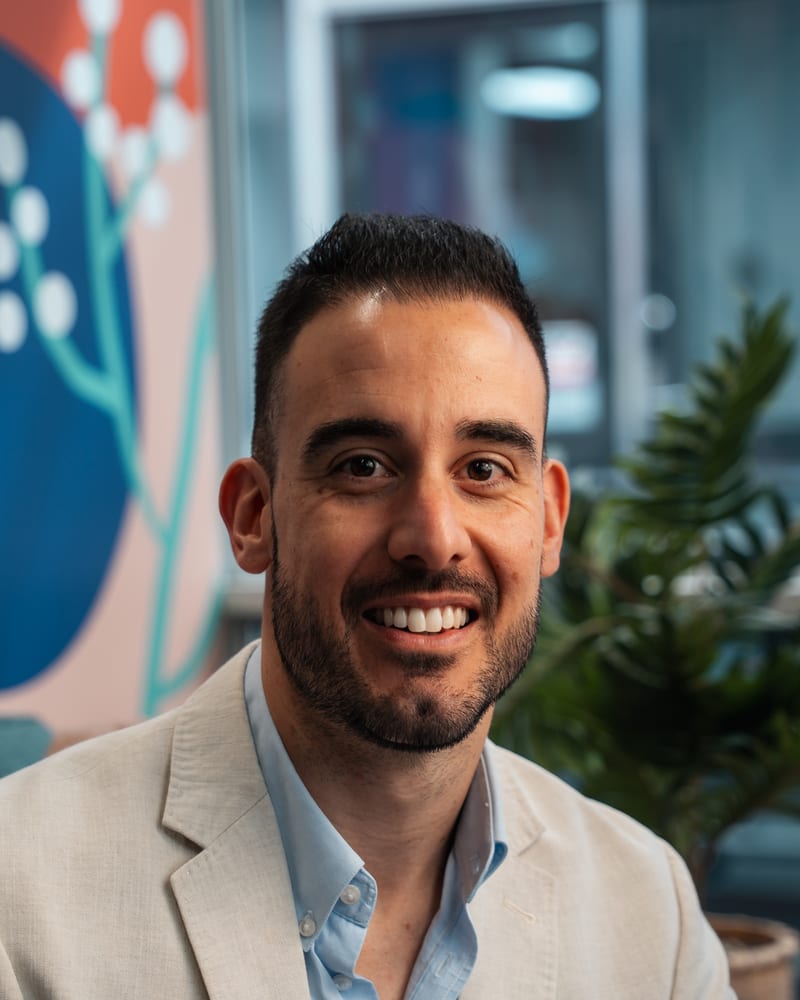
Dean Freda
Finance Broker · Tradie Specialist
Dean spent 13 years on the tools as an electrician, supervisor and business owner. He knows how you earn and which lenders back you.
Running your own show shouldn't make a loan harder to get, yet plenty of lenders treat it that way. They see "self-employed" and start looking for reasons to say no. We come at it from the other side; we're in your corner looking for the reasons to say yes.
Can I get a home loan without payslips?
With 2 clean years of financials you are a full-doc borrower and the whole market opens up. Without them, alt-doc lenders accept BAS, business bank statements or an accountant's letter instead. Neither route is lesser; they are different doors into the same building.
Do tax write-offs hurt my borrowing power?
Your accountant's job is to minimise taxable income and a lender's job is to assess it. Some lenders add back legitimate deductions, depreciation on the ute, one-off equipment purchases, when they assess what you really earn. We know which ones, and we package your file so the real story is visible.
What is a low-doc or alt-doc loan?
Both verify self-employed income without 2 years of finalised financials, typically through BAS, bank statements or an accountant's letter. The right route depends on your records and the lender, and we match the 2.
Our clients’ stories
What happens when you reach out
- 1
The conversation: 15 minutes on your goals, income and timeline, and you leave knowing where you stand.
- 2
The plan: your borrowing range, the right structure and what to do next, in plain English.
- 3
The application: packaged properly across 50+ lenders and managed through to approval.
- 4
Settlement and beyond: we stay with you after the keys, reviewing the loan as rates and life change.
Straight from our brokers
“Service like no other! I've never had a mortgage broker so on the ball. Great advice, friendly and professional.”
“Told him about a complicated financing scenario. He told us step by step the best way to proceed. I'd recommend him to anyone!”
“Outstanding service. No question was too much and no call was ever a bother. His response time reflected his work ethic.”
“Always extremely responsive and willing to go that extra yard. I could not recommend his service enough.”
Get in touch
Tell us where you’re headed
Start the conversation
Run your own numbers
Worth knowing
Can I get a home loan with 1 year of ABN income?
Some specialist lenders will consider shorter ABN history, assessed on the strength of the rest of your file. It is genuinely case by case, which is exactly where a broker earns their keep. No outcomes are promised; we tell you honestly what your file supports.
What is the difference between low-doc and alt-doc?
Both are ways of verifying self-employed income without 2 years of finalised financials. Alt-doc typically uses BAS, business bank statements or an accountant's letter. The right route depends on your records and the lender; we match the 2.
Do you understand trade businesses specifically?
Dean, who leads our tradie work, spent 13 years as an electrician, supervisor and business owner before broking. Inconsistent months, retentions, big invoices and quiet Januaries are how the industry works, and he presents them that way.
What does it cost to work with you?
Nothing. Some brokers charge for their advice; we expressly do not. We are paid by the lender you settle with, disclosed up front.
In your corner
Tell us what you're working toward and we will map the path. 1300 941 446, or book a time that suits.